Platform review
MyPeak Finance Review: Alpine Lending
How MyPeak’s Alpine business loans work, who they may suit, and what to know about repayments, access to your money and risk.
This article contains affiliate links. How this site is funded
Commercial disclosure: this article is part of a paid collaboration and contains an affiliate link. I may earn a commission through that link. The assessment distinguishes published claims from verified information.
The short version
MyPeak at a glance
- What it isA private financing platform for businesses in the Amitours mountain travel group. The focus includes transport fleets, accommodation, equipment and technology.
- Published termsThe help centre lists a €500 starting amount and typical 12–24-month loans. Check the actual campaign agreement: the rate, duration and security can differ.
- The main trade-offA specific operating business is easier to understand than a vague investment story, but several projects within one group still create concentrated exposure.
- My viewA specialist option for lenders comfortable with business credit risk and a fixed term. The specific borrower and loan agreement matter more than the travel brand.
MyPeak.finance has a more specific proposition than its name might suggest. It connects lenders with financing needs across an Alpine travel business: the vehicles taking visitors to resorts, accommodation capacity, equipment and the technology supporting those services.
I have tried MyPeak.finance. Here, I focus on how its lending model works, who it may suit and the terms that deserve attention. Platform documentation and company information were checked on 8 September 2026. Rates and security depend on the individual loan agreement; this review does not report personal investment returns.
What MyPeak finances
According to its Getting Started guide, lenders provide business loans to companies within the Amitours Group. The guide names Alps2Alps, Rock2Rocks and SkiBookers as group brands; the end-borrower for lender-funded projects is Alps2Alps OÜ. Funding supports projects such as fleet expansion, accommodation and technology improvements.
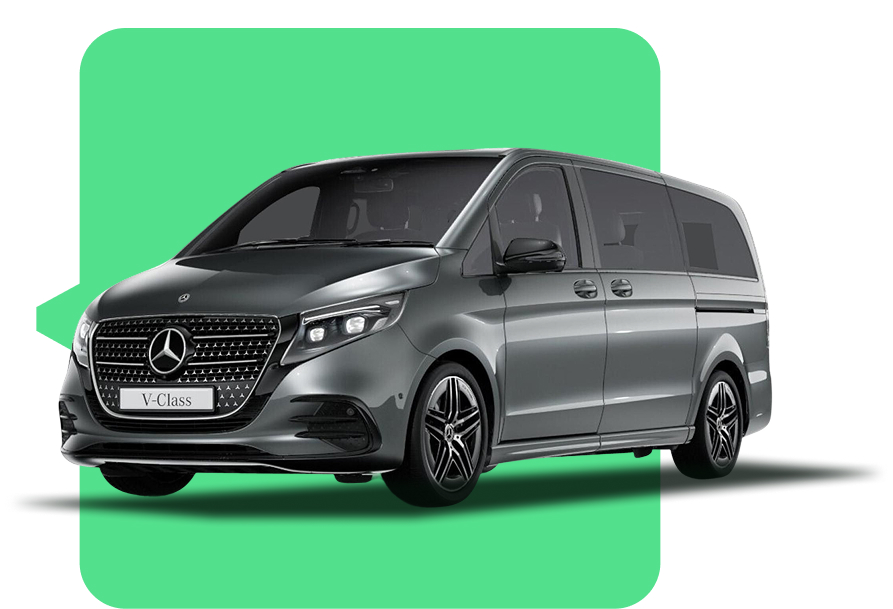
The distinction I would keep in mind is group exposure. Financing a vehicle project and an accommodation project may spread money across different activities, but those activities can still depend on the same management, customers and sources of cash.
For example, weaker demand for ski holidays could affect both transport bookings and accommodation income. Having two campaign names in a dashboard does not necessarily give you two independent sources of repayment.
Who operates the platform?
Two companies matter here, and the distinction is worth getting right before you lend.
Amitours Holding OÜ is the loan originator. Estonia's company register lists it under registration number 17355055, with the former name Mypeak.Finance OÜ, Raitis Bullits as a board member and Amitours Group SA as its shareholder.
Alps2Alps OÜ, a subsidiary of Amitours Holding, is the end-borrower. Lenders finance projects tied to the Alps2Alps business — a pioneer of Alpine mobility, and the operating company behind the figures the group publishes: revenue of roughly €20 million for 2025, projected to reach €25 million in 2026.
Both figures come from the company and are not independently audited here, and the 2026 number is a projection rather than a result. They describe the operating business rather than the lending platform, which has the shorter record of the two, so assess them separately from loan performance. The question that matters most to a lender does not change: which legal entity is named as the borrower in your agreement?
Minimum investment, terms and features
The published loan guide describes the following:
| Feature | Published position |
|---|---|
| Starting amount | €500 |
| Typical duration | 12–24 months; individual terms can differ |
| Interest payments | Monthly |
| Secondary market | Listed as unavailable |
| Auto-invest | Listed as unavailable |
Use these published terms as a starting point, then check the current campaign for its rate, fees, duration and repayment schedule. Compare the full agreement: a higher advertised rate may come with a longer commitment or different security.
How lending and repayments work
The documented sequence is to register, complete verification, transfer funds and review a financing request before accepting its agreement. MyPeak says its identity checks use Sumsub and include an identity document and liveness verification. KYC guide
Once you accept a request, money is reserved during a funding period of up to seven business days. It cannot be withdrawn or used for another loan while reserved. If the funding target is missed, the help centre says the request is cancelled and the money returns to available balance; provisionally accrued interest is cancelled too. Funding rules
The repayment guide describes monthly interest with principal returned at maturity. This is commonly called a bullet loan. Receiving monthly income therefore does not mean your original capital is gradually being returned.
For example, on a €1,000 loan with this structure, the scheduled monthly payments are interest; the €1,000 principal remains outstanding until maturity. This is an illustration of the repayment structure, not a quoted MyPeak offer. The key question is how the borrower plans to fund that final repayment: operating cash flow, asset sales or refinancing.
Can you withdraw early?
Withdrawing unused money and exiting an active loan are separate questions.
The withdrawal guide says available wallet funds can be withdrawn, with a €50 minimum, processing of up to five working days, and no platform withdrawal-request fee. Deposits use SEPA and normally take one or two working days. Withdrawals must return to the originating bank account, and the guide requires a bank PDF confirming the deposit.
For money already lent, plan to hold to maturity. There is no early-exit feature — MyPeak confirms it has been postponed — and the help centre lists no secondary market, so money committed to a loan stays committed for the full term. Size your position with that in mind.
A no-fee withdrawal request does not establish that every service is free. Check the complete fee schedule and ask how a final balance below €50 is handled.
Is MyPeak regulated?
The September 2026 check of ESMA's public register did not find an ECSPR authorization for MyPeak or Amitours Holding under the names and company numbers researched. An ECSPR licence is therefore not established by this review.
That does not determine which regulatory regime applies to the business. Before lending, confirm the legal framework and the protections attached to your agreement. Company registration and identity verification are separate from financial-services authorization. See the Estonian regulator's explanation of crowdfunding licensing.
Loan security and the risks
The security position is set out in each individual loan request, so that is the document to read before accepting one. MyPeak confirms that the loans it offers are unsecured and subordinated: no asset is pledged against them, and lenders rank behind the borrower's senior creditors if it cannot pay.
That is the most important line in this review. It does not make the platform unsuitable — subordinated lending is a normal way to finance a growing operating business, and the rate is what compensates for the position — but it does mean your return depends on the borrower trading well, rather than on anything you could claim if it does not.
Three risks matter most:
- Borrower risk: monthly interest and the final principal payment depend on the borrower's ability to pay. Late payments or default can reduce returns and put capital at risk.
- Group concentration: transport, accommodation and technology projects can all be affected by the same decline in travel demand. Several campaigns within the group do not necessarily provide independent exposure.
- Subordination risk: because the loans are unsecured and subordinated, there is no collateral to enforce and lenders sit behind senior creditors in any recovery. Financing a vehicle does not give lenders a claim over it.
I would assess the lending record using outstanding loans, late payments, defaults and recoveries, with dates and clear definitions. Those figures are more useful for judging credit performance than travel customer counts.
Who can join?
The Getting Started guide lists individual lenders from the EU/EEA excluding Latvia and Estonia, plus the UK and Switzerland. It qualifies eligibility by local rules and loan terms, so confirm your country in the current onboarding process.
For context, see my P2P lending guide and platform comparison. Compare the actual borrower structure, regulation and liquidity, rather than assuming platforms with similar headline rates work the same way.
Pros and cons
What works well
- A clearly defined focus on the mountain travel economy
- Published guidance explaining funding and repayment mechanics
- A monthly-interest structure for loans described in the help centre
What to consider
- Exposure can remain concentrated within one corporate group
- An ECSPR licence was not substantiated by the register check
- No early exit and no secondary market, so money is committed to maturity
- Loans are unsecured and subordinated, ranking behind senior creditors
FAQ
What is the minimum amount on MyPeak?+
Does monthly interest mean I can withdraw my investment?+
Are MyPeak loans secured?+
Does funding several MyPeak projects diversify my investment?+
Verdict
MyPeak is a specialist business-lending platform built around the Alpine travel economy. Its focused model and published repayment guidance make it easier to understand what the financing supports.
It may suit lenders who understand private business loans and can commit money for the agreed term. It is a poor fit for emergency savings or anyone who needs dependable access to their principal. Monthly interest is useful cash flow, but it does not remove the final repayment risk.
My priority would be the specific loan: who owes the money, how they will repay it and what rights lenders have if they cannot. Read those alongside the regulatory position and exit terms before committing. The travel business provides the context; the agreement determines the investment.
Thanks for reading.
Explore more of my experience with investing and building passive income.
Inside my portfolioKeep reading
LEI System’s prices, application and renewal terms, with a practical look at which plan suits your company.
How litigation funding works, what the public track record shows, and the fees, minimum investment, and risks to understand before committing money.
Compare plans, currency tools, team cards, and integrations, with a closer look at the charges European businesses need to factor into their decision.
A closer look at mortgage-backed projects, target returns, minimum investment, regulation, and the risks involved in lending through this real estate platform.
Explore the loan types, governance, target returns, and loyalty programme, alongside the uncertainties that come with investing through a newer lending platform.
My experience with Romanian property lending, covering collateral, minimum investment, investor fees, target returns, and the risks behind the platform’s projects.